One account, every market we offer
ExploreShort selling is a way to profit from a falling price. A short seller borrows shares, sells them at today's price, and later buys them back to return to the lender, keeping the difference if the price has dropped. If the price rises instead, the short seller loses money, and in theory that loss has no upper limit.
That asymmetry is why shorting sits at the centre of risk management in trading. This guide explains how a short sale works step by step, compares long and short positions, walks through a worked profit and loss example, and covers the costs, the risks and the alternatives.
Quick answer: Short selling is a trading strategy in which a trader borrows shares from a broker, sells them at the current market price, and later buys the same number of shares back to return them. The short seller profits if the price falls and loses if the price rises, with no cap on the potential loss.
Highlights of this article
- Short selling means selling borrowed shares now and buying them back later, hoping to buy back cheaper
- A long position profits when price rises; a short position profits when price falls
- The maximum gain on a short is the entry price (if the stock goes to zero), but the maximum loss is unlimited
- Shorting is never free: borrow fees, dividends owed to the lender and margin interest all eat into the result
- Short squeezes, share recalls and overnight gaps are the main risks, which is why a predefined stop-loss matters
- Inverse ETFs, put options and derivatives such as CFDs or perpetual futures offer short exposure without borrowing shares
Funded accounts
Ready to get funded?
Trade up to $200,000 in firm capital with static drawdown, no consistency rule, and payouts within 24 hours. Pass the challenge and keep up to 90% of your profits.
Get funded from $40Short selling at a glance
| Item | Detail |
|---|---|
| Definition | Selling borrowed shares and buying them back later to return them |
| Rule of thumb | Profit or loss per share = entry price minus exit price |
| Worked example | Short 100 shares at 100, cover at 80: profit of 2,000 USD before costs |
| When it matters | Bearish views, hedging a long portfolio, overvalued or failing companies |
| Main risk | Unlimited loss if the price rises, made worse by squeezes and gaps |
| Costs | Borrow fee, dividends owed to the lender, margin interest, commissions |
| Related terms | Margin call, short squeeze, short interest, uptick rule |
What is short selling?
Short selling is the sale of a security the seller does not own, made with the intention of buying it back later at a lower price. In stock markets, the seller borrows the shares through a broker, which sources them from its own inventory, from other clients' margin accounts or from institutional lenders.
Short selling has legitimate uses: hedging long portfolios, providing liquidity, and expressing a view that a company is overvalued, which also helps prices reflect negative information.
Long vs short: what is the difference?
A long position profits when the price rises, while a short position profits when the price falls. Going long means buying an asset you expect to gain value. Going short means selling an asset you expect to lose value.
| Long position | Short position | |
|---|---|---|
| First action | Buy | Sell (borrowed shares) |
| Closing action | Sell | Buy to cover |
| Profits when | Price rises | Price falls |
| Maximum gain | Unlimited | Entry price (stock goes to zero) |
| Maximum loss | Entry price (stock goes to zero) | Unlimited |
| Ongoing costs | Margin interest if leveraged | Borrow fee, dividends owed, margin interest |
The two positions mirror each other in direction, but not in risk.
How do you short a stock?
You short a stock by borrowing shares through a margin account, selling them, buying them back later, and returning them to the lender. In a typical brokerage account, the process runs in five steps:
- Open a margin account. Shorting is not possible in a standard cash account.
- Locate and borrow the shares. The broker must be able to borrow the shares before the sale. Heavily shorted stocks may be "hard to borrow" or unavailable.
- Sell the borrowed shares. The proceeds stay in your account as collateral, plus additional margin.
- Monitor and pay the carrying costs. You pay a borrow fee, owe any dividends, and must keep enough equity to meet the maintenance margin.
- Buy to cover and return the shares. The shares go back to the lender, and your result is the sale price minus the buyback price, minus costs.
Margin rules vary by broker and exchange. In the US, Regulation T sets 50% initial margin for stocks (for a short, the proceeds plus 50% of the position value), and FINRA requires at least 25% maintenance margin, higher for shorts; brokers often set more. If equity falls below the maintenance level, you face a margin call and may have the position closed for you.
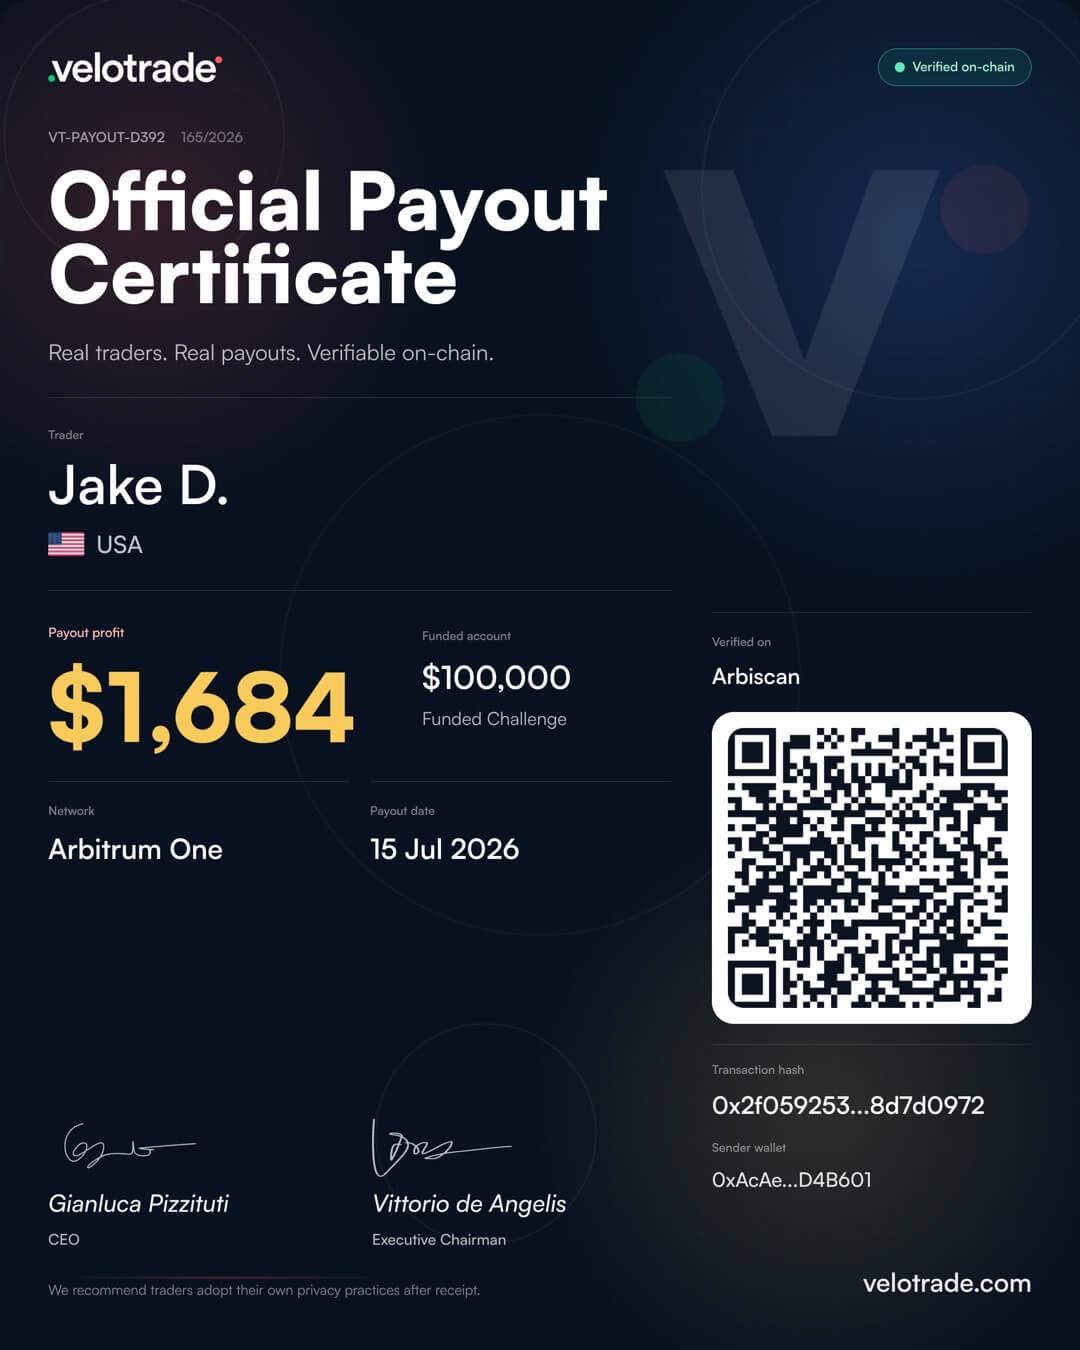
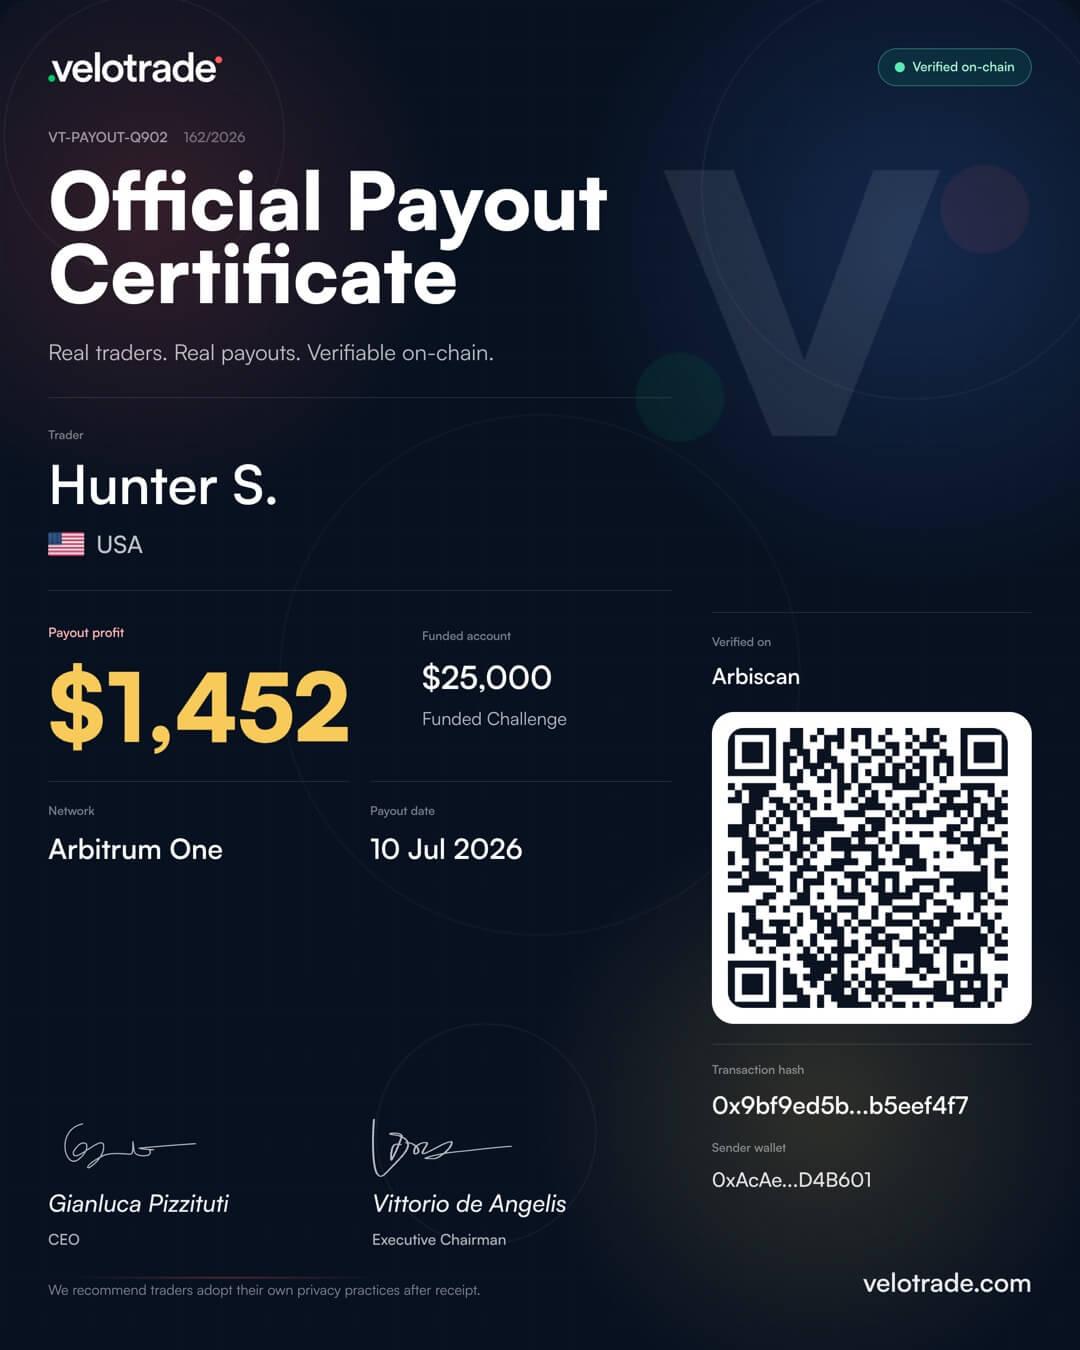
Payout proof
Fast, real payouts. Traceable on Arbitrum.
- Paid within 24 hours of approval
- Settled on Arbitrum in USDC or USDT
- Look up any transaction on Arbiscan
Worked example: short selling profit and loss
A short seller's profit or loss per share is the entry price minus the exit price. The chart below shows the result for a short position and a long position both opened at 100.
Suppose you short 100 shares at 100 USD. The sale brings in 10,000 USD.
- Price falls to 80. You buy back 100 shares for 8,000 USD. Profit = (100 minus 80) x 100 = 2,000 USD before costs.
- Price falls to 50. You buy back for 5,000 USD. Profit = (100 minus 50) x 100 = 5,000 USD.
- Price rises to 130. You buy back for 13,000 USD. Loss = (100 minus 130) x 100 = minus 3,000 USD.
- Price rises to 150. You buy back for 15,000 USD. Loss = (100 minus 150) x 100 = minus 5,000 USD.
The chart shows the asymmetry. The short gains as price falls, but the most it can make is the 100 USD entry price per share. Above the entry, the short loses more for every dollar the price rises, with no ceiling.
Now add costs. Assume the stock has an annual borrow fee of 3%, you hold for 20 days, and the company pays a 0.50 USD dividend per share during that time:
- Borrow fee = 10,000 x 3% x 20 / 365 = about 16.44 USD
- Dividend owed to the lender = 0.50 x 100 = 50 USD
- Total carrying cost = about 66.44 USD, before commissions and margin interest
On the 2,000 USD winning trade, the net profit falls to about 1,933.56 USD. On the 3,000 USD losing trade, the net loss grows to about 3,066.44 USD. Costs always work against the short seller, whichever way the price moves.
What does it cost to short a stock?
Shorting a stock costs a borrow fee, any dividends paid while the position is open, margin interest and commissions. A short therefore needs a larger move just to break even.
- Borrow fees. An annualised rate on the value of the borrowed shares, accrued daily. Hard-to-borrow stocks can cost many times more than easy ones, and the rate can change while you hold.
- Dividends owed. The lender is still entitled to any dividend, so the short seller pays an equal amount (a payment in lieu of dividend).
- Margin interest and commissions. Interest applies to any cash borrowed for margin, and commissions or spreads apply on both legs. Wide bid-ask spreads on illiquid stocks raise the round-trip cost.
What are the risks of short selling?
The main risks of short selling are unlimited losses, short squeezes, share recalls and price gaps. Each one can turn a reasonable trade into a large loss quickly.
Unlimited loss
A stock can only fall to zero, but it can rise without a ceiling. A short at 100 that doubles to 200 loses 100 USD per share. This is why short sellers size smaller and define an exit before entering.
Short squeezes
A short squeeze happens when a rising price forces short sellers to buy back their shares, and that buying pushes the price even higher. The chart below shows the typical pattern.
In the chart, short positions build up while the stock drifts lower. When a rally starts, shorts begin to cover, volume jumps, and the price climbs steeply to a squeeze peak before the move fades. Well-known examples include Volkswagen in October 2008 and GameStop in January 2021. The short squeeze guide covers the mechanics in detail.
Recalls and buy-ins
The lender can ask for the shares back at any time. If the broker cannot find replacement shares, it may close your short position through a buy-in, regardless of the current price or your plan.
Gaps
Stocks can open far from the previous close after earnings, takeover bids or other news. A stop-loss order on a short becomes a market order once triggered, so a gap up can fill it well above the stop price.
What is short interest and the uptick rule?
Short interest is the total number of shares that have been sold short and not yet covered, usually reported as a percentage of the float (the shares available for public trading). High short interest signals that many traders are betting on a decline, and it also means more potential buyers if those traders are forced to cover. Days to cover divides short interest by average daily volume.
The uptick rule restricts short selling during sharp declines. The original US uptick rule was removed in 2007; the current version, the SEC's alternative uptick rule (Rule 201), applies when a stock falls 10% or more from the previous day's close. Once triggered, short sales are generally allowed only at a price above the current best bid for the rest of that day and the following day. Other markets have their own rules.
What are the alternatives to short selling?
The main alternatives to short selling a stock are inverse ETFs, put options and derivatives such as CFDs or perpetual futures. Each gives short exposure without borrowing shares, but each has its own costs and risks.
- Inverse ETFs. These funds aim to move in the opposite direction to an index over a single day. Because they reset daily, longer-term returns can drift from the simple inverse of the index.
- Put options. A put gives the right to sell at a fixed strike price before expiry. The maximum loss for the buyer is the premium paid, which makes a put a defined-risk way to bet on a decline. See call vs put for how puts work, and selling puts and covered calls for the other side of the trade.
- CFDs and perpetual futures. These let traders short price movements without owning or borrowing the asset. They are usually leveraged, carry financing or funding costs, and can be closed out automatically if margin runs short (the guide to liquidation in trading explains how). Availability and rules vary by country.
How does short selling work in a simulated prop evaluation?
In a simulated prop evaluation, a short position follows the market price of an instrument, but no real shares are borrowed or sold. Velotrade, a multi-asset prop trading firm, runs simulated evaluation accounts across crypto, forex, stocks, index ETFs and commodities. The short seller's job is the same: define the risk before entering.
A few published rules shape how a short fits inside a Velotrade evaluation:
- The hard limits are the daily loss limit and the static maximum drawdown. The daily loss limit resets at 00:30 UTC and is set from the higher of balance or equity (5% on CLASSIC 2-Step, 4% on CLASSIC 1-Step, 3% on PRO 1-Step). A short that runs against you counts toward both, so a single squeeze can end an evaluation. The static maximum drawdown guide explains the drawdown rule.
- Position size is limited by leverage. Position size is limited only by the leverage available for each instrument, which varies by asset class.
- Costs are flat on both sides. The overnight rate is the same whether a position is long or short, and commission is charged per side.
- Single stocks have extra rules. Positions must be closed at least 24 hours before earnings and before the stock trades ex-dividend, and some single stock instruments may be available long only.
Because the account is simulated, no real shares are borrowed, so there is no lender to recall them. Gaps and fast rallies still matter, because prices follow the market.
Common short selling mistakes
- Shorting without a stop. With an open-ended loss, every short needs a predefined exit and a size that fits it.
- Fighting a strong uptrend. Valuation alone is not a timing signal.
- Forgetting carrying costs. Borrow fees and dividends can turn a small winning trade into a loss.
Broker disclosures and academic studies consistently find that most retail day traders lose money, and the asymmetric payoff of shorting makes discipline even more important. A trading journal helps you check whether your short trades actually work.
Can AI help with short selling?
AI can help screen for short candidates, flag rising short interest, and analyse your past short trades. It can also speed up testing on historical data, as described in the guides to AI trading strategies and backtesting trading strategies.
AI does not remove the core risk of shorting. A model cannot predict a takeover bid, a squeeze or a gap, and its output still needs human judgement on size and stop placement.
Frequently Asked Questions
About the author
Vittorio De Angelis
Executive Chairman
Former equity-derivatives trader at JP Morgan, Dresdner Kleinwort and Bank of America in London. Later Head of Brokerage at a global broker in Hong Kong.
View author page