Run your algo on funded capital
ExploreAlgorithmic trading strategies are trading rules written precisely enough for a computer to run them. Almost every system, from a retail bot to a fund's model, belongs to one of a handful of families, and knowing them shows what a strategy is really betting on.
This guide compares the 7 main types, works through a sizing example, and shows which fit prop firm evaluation rules.
Quick answer: The main algorithmic trading strategies are trend following, mean reversion, momentum, breakout, statistical arbitrage, market making and execution algorithms such as VWAP and TWAP. The first four bet on price direction, statistical arbitrage bets on relationships between instruments, market making earns the bid ask spread, and execution algorithms reduce the cost of filling large orders.
Highlights of this article
- Trend and momentum bet that moves continue; mean reversion bets that they fade; each fails in the conditions where the other works
- Time series momentum has been documented across 58 futures and forward markets, but published evidence is not a promise of future returns
- Market making and latency-driven strategies need speed and order volume that prop evaluations usually prohibit
- On Velotrade, bots and API trading are allowed, while grid, arbitrage, tick scalping, HFT and martingale strategies are prohibited
Run it on funded capital
Run your bot on a funded account from $40
Bots and EAs are allowed on challenge accounts, with full REST and WebSocket API access at no extra fee, no consistency rule and a static drawdown floor your risk code can rely on.
Get funded from $40Algorithmic trading strategies: key facts
| Item | Detail |
|---|---|
| Definition | A trading rule set coded so a computer can generate and execute orders without manual decisions |
| Main families | Trend following, mean reversion, momentum, breakout, statistical arbitrage, market making, execution algorithms |
| Relative value | Statistical arbitrage and pairs trading |
| Liquidity provision | Market making, earning the spread while managing inventory |
| Execution algorithms | VWAP and TWAP, which split large orders to reduce market impact |
| Biggest risk | A strategy tuned to past data that fails live because the edge was never real |
What are algorithmic trading strategies?
An algorithmic trading strategy is a set of rules with no room for interpretation. Instead of "buy when the trend looks strong", it says "buy when price closes at a 20-day high". Because the rule is exact, a program can test it on years of history and run it live.
Every strategy has a signal, a position size, exits and risk limits. The family describes the signal; the rest decides whether the system survives. For the bigger picture of how research becomes a live system, see quant trading and what algorithmic trading is.
What are the main types of algorithmic trading strategies?
| Strategy | Core bet | Works best in | Typical holding period | Main weakness | Prop evaluation fit |
|---|---|---|---|---|---|
| Trend following | Large moves persist | Sustained trends | Days to months | Many small losses in ranges | Good |
| Mean reversion | Stretched prices return to an average | Ranging markets | Hours to days | Large losses when a trend starts | Good with hard stops |
| Momentum | Recent winners keep outperforming | Persistent trends, strong sectors | Days to months | Sharp reversals | Good |
| Breakout | Price leaving a range starts a new move | Volatility expansion | Hours to weeks | False breakouts | Good |
| Statistical arbitrage | Related prices converge | Stable relationships | Days to weeks | Relationships break | Depends on the method |
| Market making | Earn the bid ask spread | Liquid, calm markets | Seconds to minutes | Inventory risk, speed | Poor |
| Execution (VWAP, TWAP) | Fill large orders cheaply | Any, as a tool | One session | Not a source of profit itself | Not a standalone strategy |
Trend following
Trend following buys rising markets and sells falling ones, holding until the trend ends. Signals include moving average crossovers or new highs over a lookback window, with trailing stops as exits.
This is one of the best documented families. Moskowitz, Ooi and Pedersen found that an instrument's past 12-month excess return positively predicted its future return across 58 futures and forward contracts, an effect that persisted for about a year before partially reversing. AQR's follow-up research built a trend strategy back to 1880 and found it consistently profitable over the following 110 years. The cost is a low win rate: trend systems lose small and often in ranges and rely on a few large winners.
Mean reversion
Mean reversion trading assumes that prices stretched far from an average will snap back. A typical system buys when price closes 2 standard deviations below a 20-period average, as with Bollinger Bands, and exits at the average. Win rates tend to be high and individual gains small.
The danger is the trade that does not revert. Without a hard stop, the system keeps buying into a falling market, and adding to a losing position is a behaviour many prop firms classify as risk abuse.
Momentum
Momentum trading overlaps with trend following but is often cross-sectional: rank many instruments by recent return, buy the strongest and avoid or short the weakest. The time series version compares each instrument with its own past. Momentum signals often use rate of change, RSI or relative strength across a basket.
Momentum suffers sharp reversals when crowded positions unwind. Several longs in assets that move together are one large bet, not several small ones.
Breakout
Breakout trading enters when price leaves a defined range, such as the highest high of the last 20 bars or an opening range. The logic is that a range break signals new information or a shift in supply and demand. Stops sit back inside the range, and volatility filters such as the ATR help avoid trading every small poke through a level.
Many breakouts fail, so these systems depend on letting the real moves run.
Statistical arbitrage
Statistical arbitrage trades relationships rather than direction. The classic form is pairs trading: find two instruments whose prices usually move together, and when the spread between them widens unusually, short the expensive one and buy the cheap one, betting the gap closes. Gatev, Goetzmann and Rouwenhorst tested pairs trading on US stocks from 1962 to 1997 and found average annualised excess returns of up to 12% for portfolios of top pairs, while noting that part of those profits may come from market microstructure effects.
The risk is that the relationship breaks permanently. On a prop account, separate statistical arbitrage from pure arbitrage. Velotrade prohibits arbitrage that exploits price differences between platforms and latency arbitrage. Our crypto arbitrage explainer shows how cross-exchange arbitrage works and why prop firms ban it. A slower relative value strategy that takes genuine market risk on instruments within one account is a different activity, but confirm it against the current rules before you run it.
Market making
A market maker posts a bid and an ask at once and earns the spread when both fill. The hard part is inventory: if buyers keep lifting your ask in a rising market, you end up short at the wrong time. Models such as Guéant, Lehalle and Fernandez-Tapia's, building on Avellaneda and Stoikov, adjust quotes to manage that inventory risk.
Market making is not suitable for a prop evaluation. It depends on constant quoting, fast cancellation and low latency, the order volume and speed prop rules target. On Velotrade, HFT that exploits latency or places excessive orders is prohibited, as are systems that place or cancel orders at extreme speed.
Execution algorithms: VWAP and TWAP
Execution algorithms do not decide what to trade. They decide how to fill an order that has already been chosen. A VWAP algorithm splits a large order across the session in proportion to expected volume, aiming to match the volume weighted average price. A TWAP algorithm splits it into equal slices over a fixed time window. Both reduce market impact and slippage on large orders.
At retail and prop sizes, good order types matter more, though VWAP remains a common benchmark and intraday reference line.
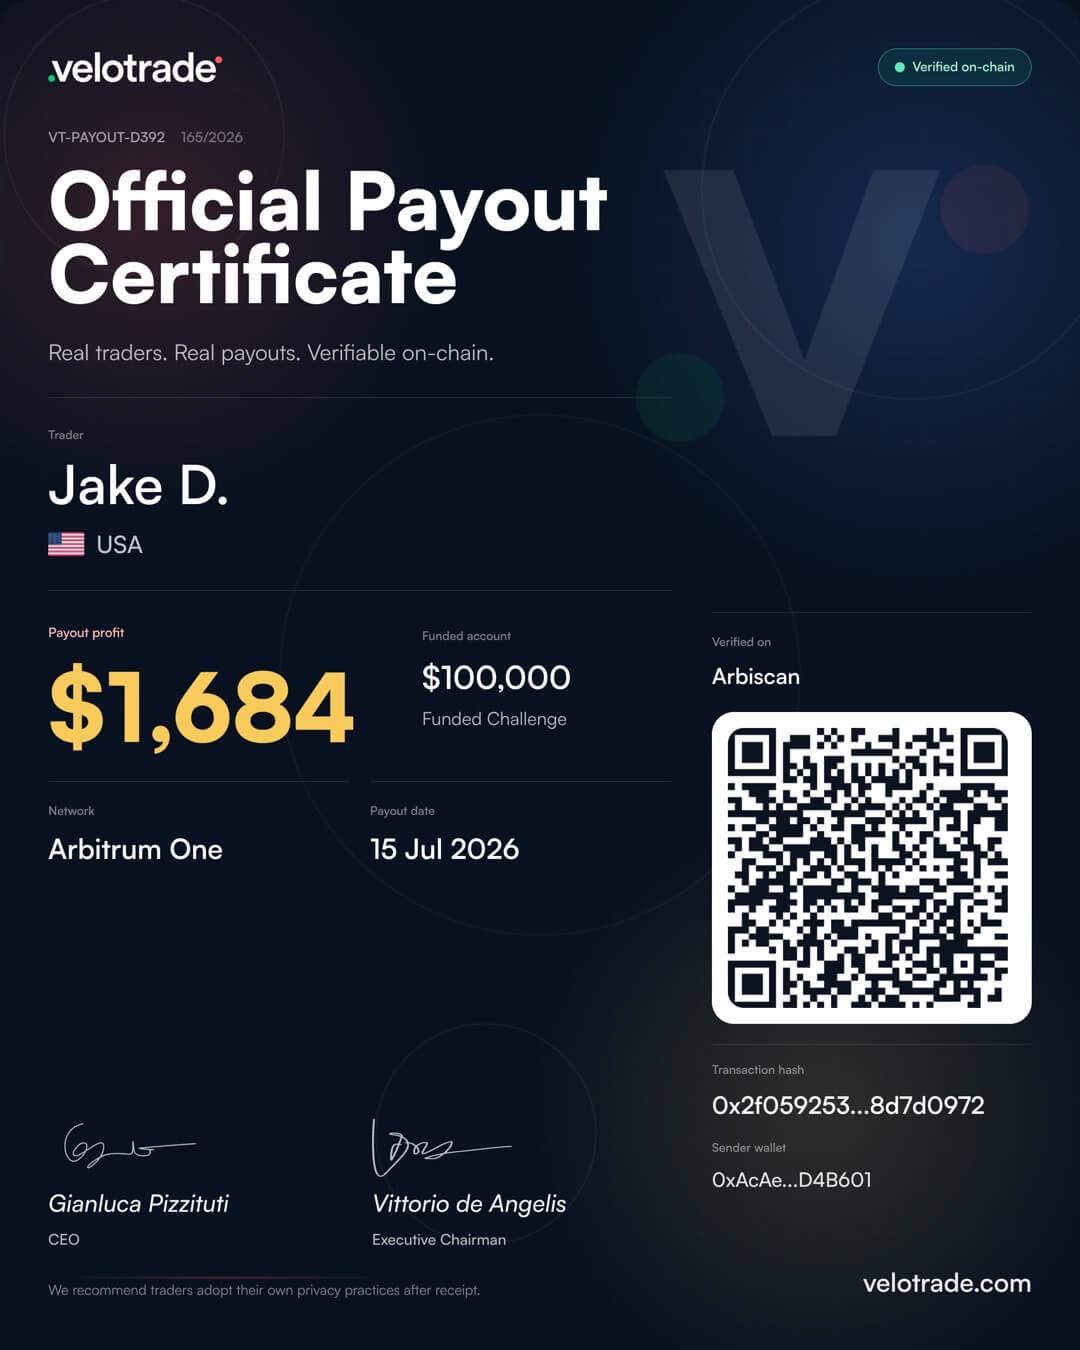
Payout proof
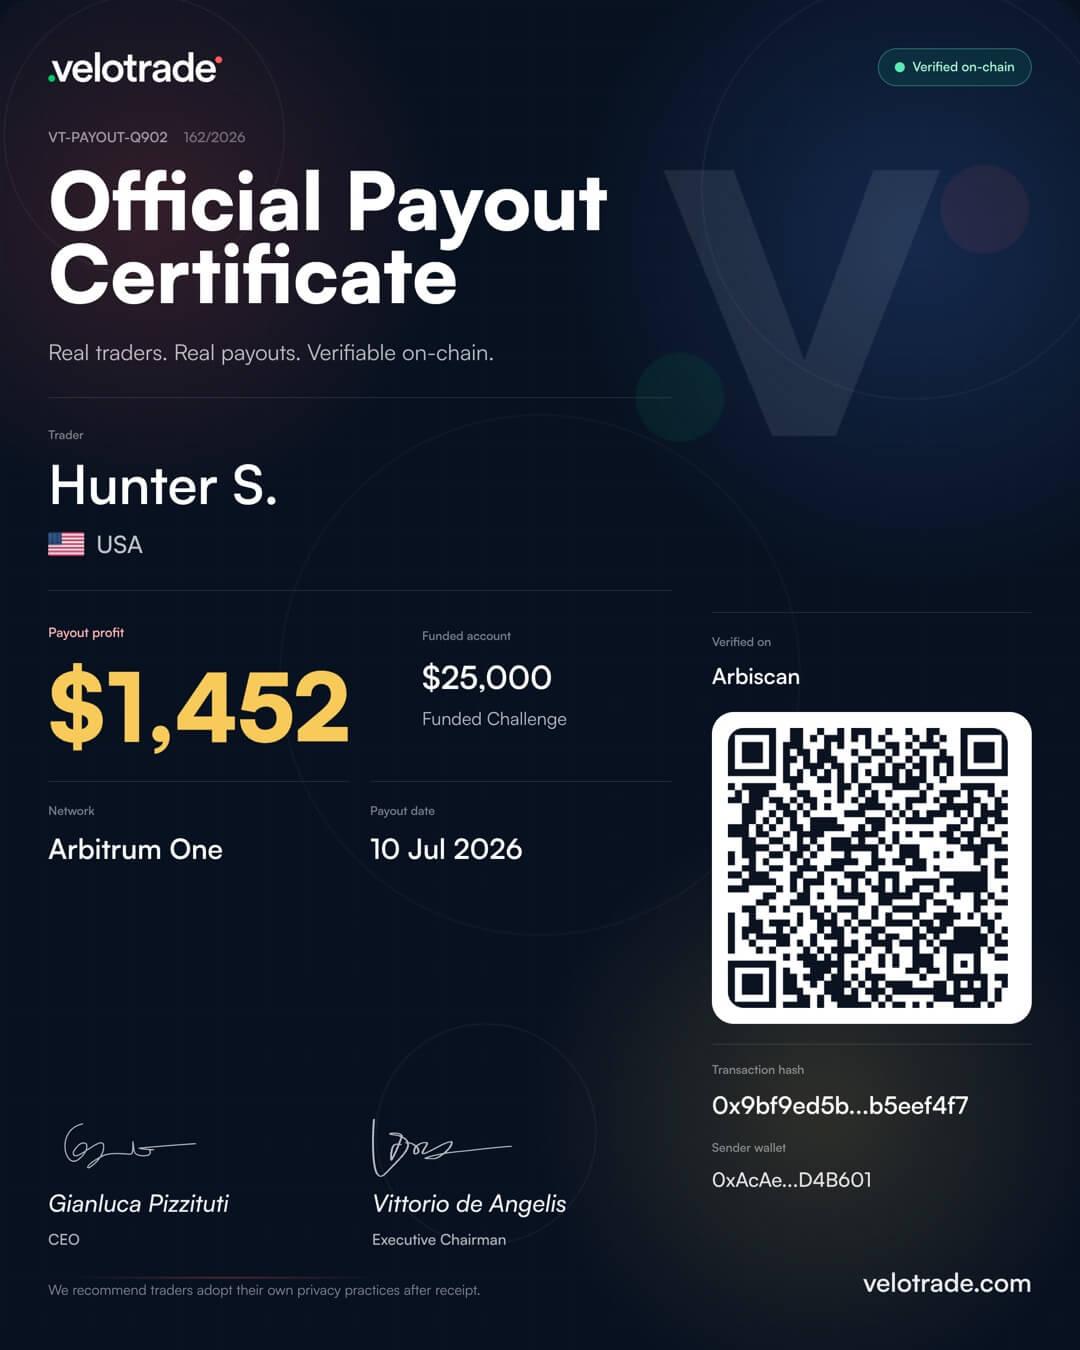
Fast, real payouts. Traceable on Arbitrum.
- Paid within 24 hours of approval
- Settled on Arbitrum in USDC or USDT
- Look up any transaction on Arbiscan
Worked example: sizing a trend-following rule for an evaluation
Take a simple breakout trend rule on BTC: buy a close above the 20-day high, place the stop 2 ATR below entry, and trail it as price rises. Run it on a Velotrade CLASSIC 2-Step 25,000 account.
| Item | Calculation | Result |
|---|---|---|
| Daily loss limit | 5% of 25,000 (reset at 00:30 UTC from the higher of balance or equity) | About 1,250 |
| Static maximum drawdown floor | 25,000 minus 10% | 22,500, fixed for the life of the phase |
| Risk per trade | 0.5% of 25,000 | 125 |
| Stop distance | 2 x ATR of 1,500 | 3,000 |
| Position size | 125 / 3,000 | 0.0417 BTC |
| Notional at 60,000 | 0.0417 x 60,000 | About 2,500 |
At 125 per full loss, the system would need 20 consecutive full losses to reach the static floor, and 10 in a single day to reach the daily limit, before costs. A trend system with a 35% win rate will see long losing streaks, so this margin is the point. The same rule risking 2% per trade would hit the floor after 5 losses.
The family decides the signal; sizing decides survival. Model other account sizes with the prop challenge calculator.
Which algorithmic trading strategies fit prop firm rules?
Prop rules evaluate skill with genuine market risk, so they target strategies that profit from technology or rule gaps. Here is how the families map to Velotrade's published rules.
| Strategy or behaviour | Status on Velotrade | Why |
|---|---|---|
| Trend following, momentum, breakout | Allowed | Directional strategies with genuine market risk |
| Mean reversion with hard stops | Allowed | Allowed as a strategy, but averaging down is flagged as risk-abusive behaviour |
| Statistical arbitrage on one account | Check the rules first | Cross-platform arbitrage is prohibited; a slower relative value strategy is a different activity |
| Market making | Not suitable | Needs constant quoting and fast cancellation that HFT rules prohibit |
| Grid trading | Prohibited | Orders at fixed intervals without an analytical basis |
| Martingale | Prohibited | High-risk position doubling |
| Tick scalping, HFT, latency arbitrage | Prohibited | Exploits speed or feed behaviour rather than market views |
| Coordinated multi-account bots | Prohibited | Removes genuine risk across accounts |
For background on why fixed-interval systems fail this test, see our educational guide to how grid trading bots work.
Beyond the list, two account rules shape every strategy. The daily loss limit ranges from 3% to 5% by plan and resets at 00:30 UTC from the higher of balance or equity, and the maximum drawdown is static, a fixed floor from the starting balance. Velotrade has no consistency rule, which suits trend and breakout systems that make most of their profit on a few strong days.
Automation itself is not the issue: Velotrade allows EAs, bots and AI-assisted strategies with DXtrade REST and WebSocket API access on every account, with no fee and no approval.
How do you choose and test an algorithmic trading strategy?
Pick the family that matches how you already think about markets, then make it testable:
- Write the rule as code-ready logic. Entry, exit, stop and size, with no discretion. If it cannot be an if statement, it is not ready.
- Backtest with real costs. Include commission, slippage and overnight fees, and keep an out-of-sample period. See backtesting trading strategies.
- Prototype fast. Pine Script on TradingView is the quickest way to test bar-based rules on charts.
- Build the live version. How to build a trading bot covers the full build, and the DXtrade API setup guide covers connecting it to a Velotrade account.
- Forward test at small size before trusting the backtest.
For the discretionary versions of each family, see the trading strategies library, or follow the full algo and quant trading track.
Velotrade provides education and simulated trading only. It is not a broker, bank or regulated financial institution, and nothing in this article is investment advice. Published research describes historical results, which do not predict future performance.
Sources
- Moskowitz, Ooi and Pedersen, "Time Series Momentum" (AQR): 12-month return predictability across 58 futures and forward contracts.
- Hurst, Ooi and Pedersen, "A Century of Evidence on Trend-Following Investing" (AQR): trend following tested back to 1880.
- Gatev, Goetzmann and Rouwenhorst, "Pairs Trading: Performance of a Relative Value Arbitrage Rule" (NBER): pairs trading on US stocks, 1962 to 1997.
- Guéant, Lehalle and Fernandez-Tapia, "Dealing with the Inventory Risk. A solution to the market making problem" (arXiv): market making and inventory risk.
- Investopedia, "Statistical Arbitrage Simplified: Essential Strategies and Risks": definition and risks of statistical arbitrage.
- Investopedia, "How Market Makers Enhance Liquidity and Profit from Spreads": how market makers quote and earn the spread.
- Investopedia, "Volume-Weighted Average Price (VWAP)": VWAP definition and calculation.
- Investopedia, "Basics of Algorithmic Trading: Concepts and Examples": overview of common algorithmic strategy types.
Frequently Asked Questions
About the author
Vittorio De Angelis
Executive Chairman
Former equity-derivatives trader at JP Morgan, Dresdner Kleinwort and Bank of America in London. Later Head of Brokerage at a global broker in Hong Kong.
Velotrade was founded in Hong Kong in 2016 by a team from JP Morgan, Dresdner Kleinwort and Bank of America, has paid out over $2.5 billion to its trade-finance clients, and has been featured in Bloomberg, the Financial Times, the Wall Street Journal and on Nasdaq. Its prop trading evaluations are simulated and educational.
View author page